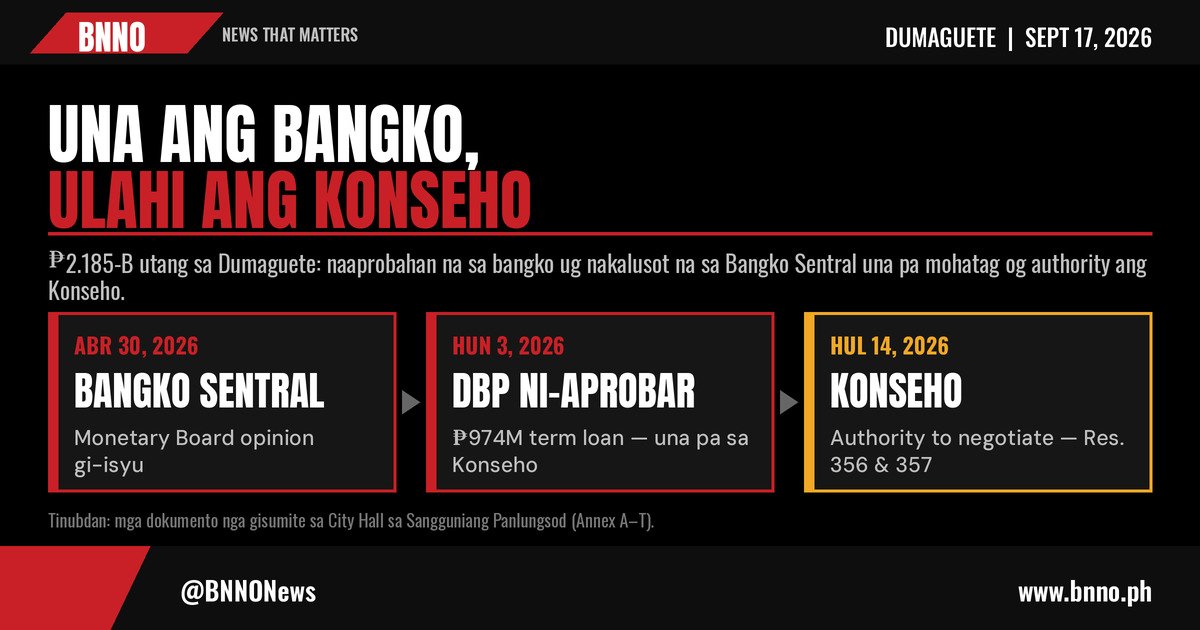
The bundle City Administrator Neil Ray Lagahit brought to the Sangguniang Panlungsod was meant to prove that “no shortcuts were taken.” Read by date, it proves the opposite: a loan applied for in February, certified in March, cleared by the central bank in April and approved by the Development Bank of the Philippines on June 3 — six weeks before the Council voted, on July 14, to let the mayor start negotiating.
DUMAGUETE CITY — The Development Bank of the Philippines approved a ₱974-million term loan for the City of Dumaguete on June 3, 2026. The Sangguniang Panlungsod granted Mayor Manuel Sagarbarria authority to negotiate that loan on July 14, 2026.
Those two dates, both drawn from documents the executive department itself submitted to the Council, are the heart of the matter. Everything the Council has voted on since — the July authority to negotiate, the August referral, the September 8 borrowing ordinances passed on second and third reading in a single session — has been a vote on an outcome that the banks and City Hall had already settled between themselves.
The submission was City Hall’s answer to three councilors, Franklin Esmeña, Renz Macion and Rey Lyndon Lawas, who wrote the mayor on September 4 asking for the negotiation letters, the banks’ responses and “all other relevant communications.” It is fronted by a six-page chronology from the Office of the City Legal Officer asserting that every step was taken “in strict accordance with law, in their proper sequence,” and closing with the line: “The record speaks for itself.”
It does. Not in the way intended.
The application City Hall says it never filed
The chronology’s central claim is that DBP’s June 3 approval was a routine bank formality and “does not, however, constitute an official loan application, as the City has yet to submit any such application to the bank.”
The bundle contradicts this on four separate pages.
The mayor’s own February 10, 2026 letter to the Bureau of Local Government Finance opens with the words “Relative to the loan application of the Local Government Unit of the City of Dumaguete with the Development Bank of the Philippines and Landbank of the Philippines.” The BLGF’s March 12 certificate is issued “relative to its loan application.” The BLGF’s same-day letter to the Acting City Treasurer refers, again, to “the loan application of Dumaguete City.” And DBP’s approval letter, in both its June 3 and August 12 versions, approves “a contract of loan applied for.”
Banks do not approve term loans that were never applied for. DBP’s approval came with a four-page term sheet, an availability period running three years from the date of notice, and an automatic-cancellation clause if the loan documents were not executed within a year of signing. That is a credit decision, not a brochure.
The Council struck the word “apply.” The application had already been granted.
The detail that best captures the sequence is buried in the July 14 resolutions. The mayor’s July 10 letters asked the Council for authority “to apply and negotiate.” At the instance of the chair of the Committee on Rules, Councilor Jason Patrick Lagahit, the Council resolved to strike the word “apply” and keep only “negotiate.”
By then the application was five months old and approved. The Council was carefully limiting an authority that had already been exceeded before it was requested.
The numbers existed before the plan did
The chronology sets out an eight-step process it says the City followed: identify the project in the Annual Investment Plan, prepare the cost estimate, then solicit bank offers.
The annexes reverse it. Land Bank’s offer sheet, Annex A, is dated January 5, 2026 and already carries the precise figures the City would later adopt: ₱1,948 million for the four-storey market and ₱237 million for the City Hall extension. The City Engineer’s Program of Work and cost estimate bearing those numbers are dated January 16 and 18. The projects were placed in the 2026 Annual Investment Plan by addendum on July 7.
A bank quoted the project to the peso eleven days before the City’s engineers wrote down the price, and six months before the City’s planning body adopted the project. Who gave Land Bank the figures in December, and on what basis, is a question the chronology does not ask.
A “negotiation” that changed nothing
If the July authority was meant to begin negotiations, the record shows none occurred. Both banks’ July 23 letters open with the sentence “This is to reiterate our offer” and reproduce, word for word, the terms they had offered in January and February. The Local Finance Committee then met on July 31 to evaluate those reiterated offers, and declared them superior to a Veterans Bank proposal dated February 12.
The Veterans Bank episode adds the one document in this record that speaks to intent. In a July 23 letter, the bank recounts that a City Hall officer, Leonidasa C. Oira, visited its Dumaguete branch on July 21 and asked that the February 12 proposal be re-dated to July 23, with the same terms. The bank declined. A February proposal carrying a July date would have sat comfortably inside the Council’s July 14 authority. The bank’s refusal is why it does not.
The billion-peso condition that vanished
The mayor’s August 27 letters told the Council the interest rate was “fixed at 4.50% per annum.” The City’s Feasibility Study Committee, responding to the independent reviewers on August 25, went further: fixed for the full 15-year term, no repricing.
DBP’s June 3 term sheet, in the executive’s own bundle, defines the condition behind that 4.5 percent. The rate holds only with “maintenance of at least ₱1.0 Billion in CASA deposits.” Otherwise the loan reprices quarterly at three-month BVAL plus spread or 5.50 percent, whichever is higher. The City’s total revenue for 2022, per the financial statements in the same bundle, was ₱1.22 billion.
DBP’s revised term sheet of August 12 deleted both sentences. The draft loan agreement transmitted to the Council on August 27 keeps the repricing machinery and leaves the required deposit balance blank. The Council was told “fixed.” The number that made it conditional was in City Hall’s files since June.
Four days before the vote, an admission
On September 4, the City Legal Officer wrote both banks asking them to delete the repricing clauses from the draft agreements, “since the loan shall bear a fixed interest rate of 4.5% per annum for the entire term of the loan.” That request is an acknowledgment that, as drafted, the loans were not fixed-rate. No reply from either bank appears in the bundle. The Council passed the ordinances on September 8, adopting agreements “as amended” by amendments the banks had not yet accepted.
The Council as after-the-fact endorser
Read together, the sequence is a loan process run backward. Terms were set with the banks in January and February. The regulatory certifications were obtained in March and April. A bank approved the loan in June. Only then was the Council asked to authorize negotiation, and its authority was then used to certify as “negotiated” a set of terms that had not moved. When the contracts turned out not to match what the Council had been told, City Hall asked the banks to change the contracts rather than tell the Council the truth, and the Council voted before the banks answered.
The Council has not been the check the Local Government Code makes it. It has been the last signature on a document already drafted.
The Remollo detour
The chronology devotes its final section to former Mayor Felipe Antonio Remollo, citing a 2023 BLGF application for in projects filed “sans any authority from the City Council,” and a certification from the Council secretary, issued September 8, 2026, the day of the vote, that Remollo never sought such authority.
The comparison does not survive the bundle’s own annexes. BLGF flagged the 2023 application as incomplete in January 2024 and it went no further: no certificate, no Monetary Board opinion, no bank approval, no request to the Council. DBP’s own 2023 letter to Remollo asked him to submit a Sanggunian resolution before proceeding. An application that stopped at the paperwork stage is not a precedent for a bank approval obtained six weeks ahead of council authority. Whether the previous mayor’s incomplete file belongs in a defense of this loan at all is a question for the officials who included it.
What the documents still do not answer
Where the January figures came from, and who supplied them to Land Bank. Whether the banks have accepted the September 4 deletions, or whether the mayor will sign a repricing contract under an ordinance that says “fixed.” What deposit balance DBP will write into the blank. Why the Council was told the rate was fixed when the June 3 term sheet was in City Hall’s possession. And whether the July 21 request to re-date the Veterans Bank proposal was an individual’s initiative or an instruction.
City Hall submitted these documents to prove the process was orderly. What they show is a process in which the Council’s role was designed to come last.